
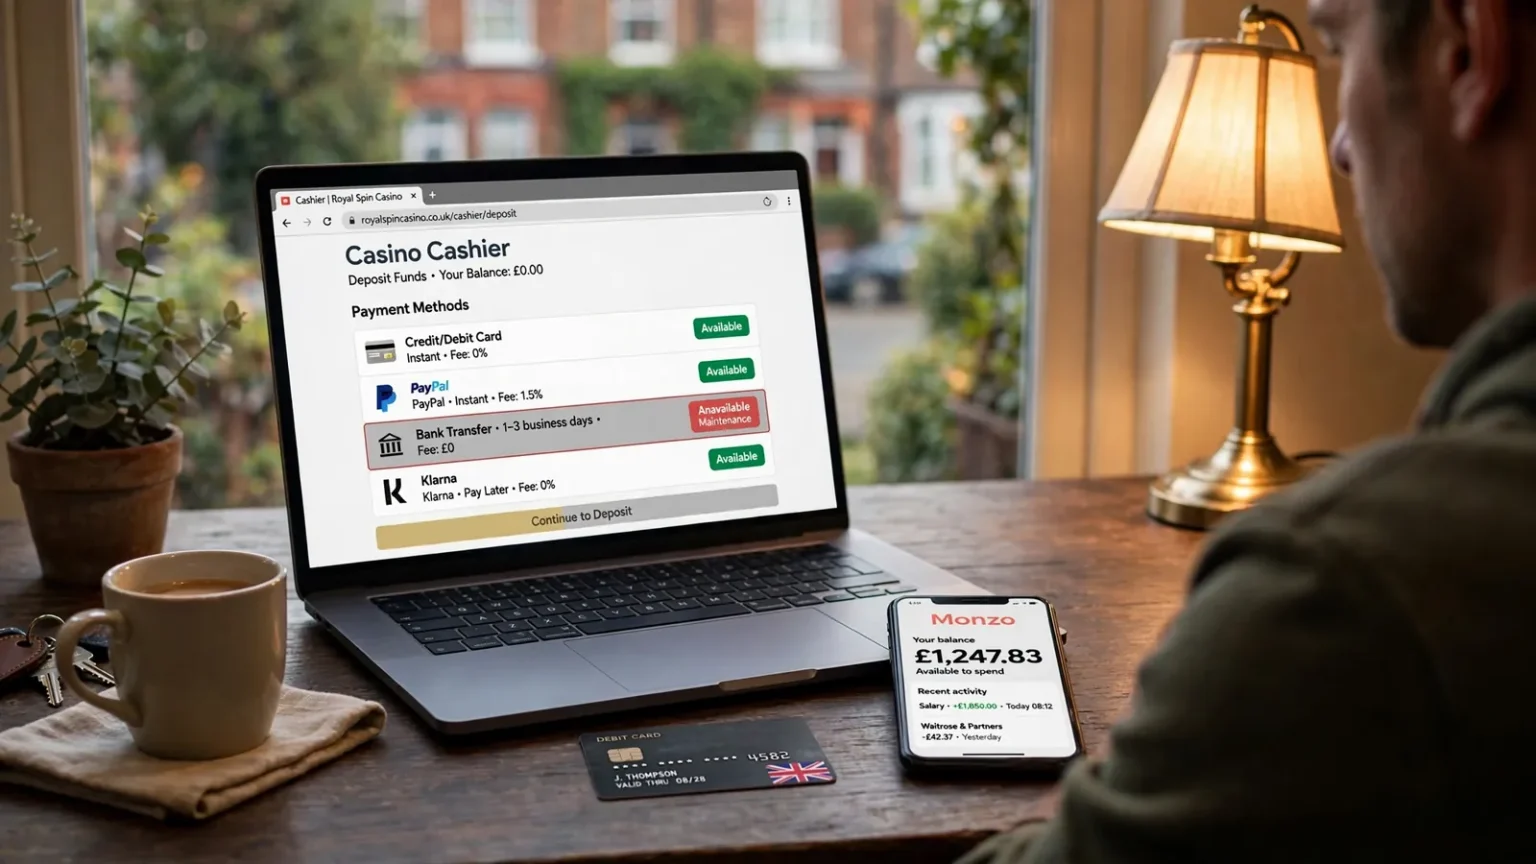
Casino cashier options can vary by operator and account, so a general payments page does not confirm that Entropay is available.
Entropay and the UK Casino Cashier
A payment logo on a casino page can look like a settled promise. It is not. Cashier options can vary between operators and accounts, and a method named in general information may not be available for a particular UK customer. For anyone looking for Entropay casinos in the UK, the practical starting point is therefore the cashier itself: acceptance needs to be visible there, not inferred from an old mention, a familiar brand or a list assembled elsewhere.
Entropay acceptance at a UK casino cannot be assumed. That is not a verdict on every operator’s systems; it is a reason to treat the method as unconfirmed until an individual casino displays it as available. Payment arrangements are operational details, not permanent features of a brand. A page may remain online after the cashier has changed, and a method offered in one setting may not appear in another.
The cashier is the point where a general claim meets the account. It shows which payment choices are enabled at that moment and for that customer. A casino’s broader payments page can still be useful as orientation, but it does not settle availability. For a method such as Entropay, a mention without a live cashier option leaves the important question open.
That distinction matters because “accepts” can be used loosely. It may mean a method appeared in a review, was supported in the past, or is available somewhere within a wider group of services. None of those meanings confirms that the method can be selected at a specific UK casino now. The cashier is less romantic than a list of logos, but more useful.
Specialist casino reviews list Visa and Mastercard among payment methods, while also noting that current UK availability and card-product eligibility need to be checked in the cashier. This is a sensible distinction: a payment brand may be familiar, yet the relevant option still depends on what the operator makes available. The same caution applies to Entropay. A general reference to a payment service is not proof that a casino’s live cashier accepts it.
Casino Payments & Withdrawals in the UK
A specialist review also describes GBP as supported on the sites it covers. That does not remove the need to check an account’s currency before the first transaction. If the account is set to another currency, the payment can involve conversion. Currency is part of the cashier’s practical information, not a decorative setting buried in account preferences.
The first check is narrow. Does Entropay appear among the methods that can be selected in the account’s cashier? This is different from asking how much can be paid, whether a method can later receive funds, or what charges might apply. Those are separate conditions. A method can be present without every transaction term being identical, and a method that is absent cannot be made available by a favourable assumption about its costs or capabilities.
This also explains why broad phrases such as “online casinos that take Entropay” can mislead when detached from a current account view. A list may collapse distinct operators, time periods and payment arrangements into one apparent answer. The cashier restores the missing context. It is specific to the casino and the account, and it avoids turning a historical listing into a present-tense guarantee.
Casinos That Accept iDEAL in the UK: How to Check
There is a wider lesson in the modesty of this check. Digital payment systems are often presented as frictionless, as if a method were simply switched on everywhere at once. In practice, the choice belongs to each operator’s cashier, while the player encounters it through an individual account. A payment name can travel easily across websites; acceptance does not travel with it.
For that reason, Entropay should be treated as unavailable for planning purposes unless it is plainly offered by the casino in question. This is not a ranking of operators, nor a claim that another payment method is better. UK casinos commonly accept debit cards, including Visa and Mastercard, but even familiar card brands still call for a cashier check where availability and eligible card products are concerned.
The live cashier is the place to establish whether that has changed for a particular account. Only after availability is established do the other questions begin—what the payment conditions are, how funds can move, and what the transaction may cost. First, the option must exist.
Attention: Entropay acceptance cannot be assumed based on general lists or logos; it must be confirmed directly within the live cashier of your individual account.
Best casino sites in the UK
- BritsinoBonus: Welcome Package – Get your £2,200 + 2,000 FS · Payout speed: 1-3 business days
- BeOnBetBonus: 100% up to €500 + 100 FS · Payout speed: 1-3 business days
- Revery PlayBonus: 100% up to€1,000+ 100 FS · Payout speed: 1-3 business days
- EvoSpinBonus: 125% up to €2500 + 125 Free Spins · Payout speed: 1-3 business days
- WinBeastBonus: €5000 + 500 FS + €650 Freebet · Payout speed: 1-3 business days
- SpinFormulaBonus: 550% Up To £15,000 + 550 FS · Payout speed: 1-3 business days
- JetsetspinsBonus: 200% Bonus + 100 Free Spins + Free Royal Wheel · Payout speed: 1-3 business days
- NightWinBonus: £900 + 400 free spins · Payout speed: 1-3 business days
- NightLuckBonus: Welcome Pack + 805% Up To 6400€ + 280 FS · Payout speed: 1-3 business days
What an Online Casino Payment Route Needs to Do
A payment route has two separate jobs: carry funds into a casino account and, where supported, provide a way for money to travel back out. Those jobs are easy to blur because a deposit button can make a method look like a complete solution. It is not. A method may be available for deposits while withdrawals follow a different route, or may not be offered for payouts at all.
That distinction matters when considering Entropay and UK casino play. The name of a payment service, or a claim that it works for deposits, does not establish that a particular casino accepts it, still supports it, or can return funds through it. Nor does it establish that the method meets the operator’s conditions for a customer’s account. A deposit route and a full payment route are not interchangeable descriptions.
Money in is only half the journey
A deposit method needs to move money from a customer’s payment account into the casino balance. A withdrawal route needs to do something different: deliver eligible funds back to a customer through a method the operator can use. Some products are explicitly deposit-only. Paysafecard, for instance, is a prepaid voucher for deposits rather than a route for receiving casino withdrawals.
The distinction is practical, not merely technical. A customer could be able to fund an account using one method and still need another means of receiving a payout. That does not make the deposit method useless; it means its role is limited. Trouble begins when a deposit option is mistaken for a promise about how winnings will be paid.
Casinos That Accept Ethereum in the UK
The payment route also sits within the operator’s controls. UK anti-money laundering rules generally require a payout to go back to the original payment source. Returning funds to that source is also a common anti-fraud measure. An alternative route may involve further verification. The starting method can therefore shape the return journey, even where the withdrawal itself is handled separately.
This is the logic behind closed-loop rules: money is not treated as if it can simply enter by any door and leave through any other. The route has a history. The operator may need to establish that the destination belongs to the same customer and is an acceptable place to send the funds. A second method is not automatically a substitute for the first.
A brand name is not a route map
The phrase “Entropay online casino” can sound as though it names a settled arrangement: a service on one side, a casino on the other, and a predictable passage between them. In practice, payment compatibility depends on what the operator supports and what the payment product can do. A familiar label alone cannot answer both questions.
Nor does a deposit transaction, if one is possible, prove that withdrawals will return through Entropay. The operator may require the original source to receive the payout, or may ask for additional verification before using an alternative. Those are separate questions from whether a deposit can be made. Treating them as one obscures the point at which a payment route can fail the customer’s expectations.
Do
- Separate deposit ability from withdrawal support
- Verify if the operator permits the route for your specific account
- Check if a method can receive a payout
Don’t
- Assume a deposit option is a complete payment route
- Rely on a brand name as a route map
- Mistake a deposit button for a payout promise
The same caution applies to descriptions of an “Entropay casino” or a casino “with Entropay”. Such wording may refer only to a deposit option, may be out of date, or may not apply to every account. It does not by itself demonstrate a complete in-and-out route. A list described as the best or top Entropay casinos would be particularly misleading if it implied confirmed deposit and withdrawal support without establishing both.
A useful way to think about any payment method is to separate three things: whether it can fund the account, whether it can receive a withdrawal, and whether the operator permits that route for the account in question. The answer to one does not settle the others. The distinction is modest, but consequential.
The route has to make sense at both ends
A payment system is not fully described by its entrance. For real-money play, the return path matters too, because funds may have to go back to their original source and alternatives may bring further checks. That principle does not confirm Entropay acceptance at any UK casino; it explains why deposit compatibility alone would not be enough to establish a usable route.
The neatest arrangement is one whose movement can be understood from start to finish: a supported source funds the account, and the operator has a compliant way to return money to that source or verify an acceptable alternative. Where those ends do not match, the route may involve another method or further checks. It is not a defect in the arithmetic. It is the system doing what it was designed to do.
A payment button is an entrance, not a map.
Casinos That Accept AstroPay in the UK
Checking a Casino’s Deposit and Withdrawal Terms
A payment method’s name is only part of the terms that govern a transaction. The cashier may also show a minimum deposit, a maximum amount for a single payment, or separate ceilings over a day or month. These figures can differ by method and account status, so a limit attached to one route should not be assumed to apply to another. Entropay-related wording, where it appears in a casino’s information, would not by itself establish what amount an account could deposit.
A specialist review has reported minimum deposits in the £10–£20 range, with the figure depending on the selected method. That is a reported range, not a fixed UK-wide rule: the current cashier terms for the specific account are the relevant figures. A minimum is a threshold for a transaction, not a recommended amount to deposit. It also says nothing about the maximum the casino or payment route will permit.
The upper limit can be just as important. A casino may state one cap for a single deposit and different caps across a day or month. The applicable figure may also depend on account status. These are separate constraints, not interchangeable descriptions of one limit. A payment below the single-transaction ceiling could still be affected by a wider account-level restriction; the cashier’s displayed terms should make clear which measure applies.
Account status matters because the figure shown for one account may not settle what another account can do. A term may distinguish between accounts or transaction circumstances without changing the method’s general description. If the cashier displays a lower permitted amount than a broad payment information page, the live account-specific figure is the practical one to rely on. General descriptions can age; the transaction screen is closer to the decision being made.
Transaction limits, including minimum deposits and maximum ceilings, can vary by payment method and account status, meaning terms for one route may not apply to another.
The withdrawal side deserves its own reading. Deposit terms and withdrawal terms are not synonyms, and a deposit threshold does not establish a withdrawal threshold. Where the operator publishes withdrawal conditions or amount limits, those should be read separately rather than inferred from the deposit panel. The point here is not to assume a particular limit, but to avoid carrying one figure across two different transactions.
Terms can also be presented in more than one place: a cashier panel, payment information, or account conditions. When figures differ, the discrepancy should be resolved before a transaction rather than treated as permission to choose whichever figure is more convenient. The relevant detail is the one that applies to the selected method and account at the time. It is a modest discipline, but money has a way of making small print unusually legible.
For a proposed deposit, the useful comparison is therefore between the amount intended and the cashier’s minimum and maximum for that transaction, alongside any daily or monthly ceiling shown for the account. For a proposed withdrawal, the withdrawal terms need to be checked independently. None of these figures can be safely inferred from a method’s name, from an old description, or from what another customer’s account displayed.
The distinction is plain, if not especially glamorous: minimums set an entry point; maximums restrict scale; account status can affect the applicable ceiling. The amounts belong to the current terms, not to a general idea of how a payment method behaves. No amount should be entered on the strength of a remembered figure.
That is the arithmetic.
Casinos that accept Giropay in the UK: cashier checks
Payment Costs Are More Than a Visible Fee
A payment can look inexpensive because the cashier shows no charge, or because it displays a single flat fee. Neither detail necessarily captures the full cost. Money may pass through several parties before it reaches a casino account, and each part of that route can apply its own charge or exchange rate. A specialist review identifies casino charges, payment-provider fees, issuer or bank fees, currency-conversion spread and network fees as possible components. Which ones apply depends on the transaction; the visible line in a cashier is not a complete bill.
For someone considering Entropay online casinos in the UK, that distinction matters before any method is treated as economical. A fee attached to a payment service is only one part of the calculation. The casino may set a charge of its own, while a provider or bank may impose a separate one. A network fee can also arise where the payment route involves a network that charges for processing. These costs need not appear together, or in the same place.
Currency conversion is less conspicuous than a stated charge. If a casino account and payment account use different currencies, the conversion rate can include a spread: the difference between the rate used for the transaction and a reference rate. That difference may be folded into the amount converted rather than presented as a separate fee. A specialist review notes that this spread can exceed a visible flat charge. The comparison is therefore not simply “fee or no fee”. It is the total value lost across the transaction.
The amount sent also changes what a charge means. A flat charge and a percentage-based cost do not behave alike as the transaction grows or shrinks. Even when the cashier’s displayed fee remains unchanged, a conversion spread or provider charge can alter the effective cost. Conversely, a route with no obvious flat charge is not automatically free. The arithmetic belongs to the actual amount, currency and route, not to a label such as “free deposit”.
Total Cost Components
Beyond the visible cashier fee, the total cost of a transaction may include payment-provider fees, issuer or bank fees, network fees, and the currency-conversion spread.
This is why a universal cheapest method cannot be named from the fee line alone. A specialist review’s comparison principle is to weigh the casino’s charge against provider fees, currency spread and any network cost for the amount being sent. That is a transaction-level comparison, not a permanent league table: rates, account settings and charges can differ. One method can look cheaper in one set of circumstances and cost more in another.
A careful comparison keeps the categories separate. First comes any charge stated by the casino. Then come costs imposed outside it by the payment provider, card issuer or bank, where applicable. Conversion belongs in its own column, even if the provider hides it inside the exchange rate. Network costs should not be overlooked merely because they do not resemble a conventional service fee. Adding these elements gives a clearer picture than treating the cashier’s headline figure as the whole expense.
The same discipline applies to mobile payments. A smaller screen may make it easier to notice a prominent charge and harder to inspect supporting terms, but the underlying cost categories do not change with the device. A displayed amount should be read alongside the terms governing the payment account and its currency. Convenience of presentation is not evidence of a lower total cost.
Casinos That Accept Interac in the UK: Payment Guide
In the end, “no fee” is a narrow statement, not a verdict on value. The less visible costs may sit with a bank, provider, conversion rate or network rather than the casino. Compare the complete route for the intended transaction, and treat any single advertised charge as one piece of the account. Small print has company.
Real-Money Play and the Route Funds Take Back
A casino withdrawal is not simply a payment sent in reverse. The route matters because anti-money laundering controls are designed to keep funds moving between accounts that can be linked to the same customer. In the UK, payouts are generally expected to return to the original payment source. This is part of the framework for real-money play, not merely a preference set by a cashier.
That closed-loop approach can shape what happens after a win. If a deposit came from a particular payment source, the casino may direct the corresponding payout back there rather than send it to a newly nominated account. The point is traceability: money entering and leaving through a recognised source is easier to associate with the customer and the original transaction.
An alternative destination may therefore prompt additional checks. A different account or payment route does not automatically mean a payout cannot be made, but it can raise questions about ownership and the reason for changing the route. Further verification may be required before the casino can proceed. The exact handling depends on the operator’s process and the circumstances of the transaction; there is no single alternative route that can be assumed to work everywhere.
Closed-Loop Rules
UK anti-money laundering rules generally require payouts to return to the original payment source; using an alternative route may trigger additional verification.
This is why the name of a payment method, on its own, says little about how a withdrawal will be handled. Someone looking at Entropay for real-money casino play in the UK would need to distinguish between a method being mentioned as a deposit option and a route that can receive a payout under the casino’s rules. The relevant question is not only whether funds can go in, but whether the same source can be used for a return and what checks apply if it cannot.
Payment systems often present themselves as neat circles: deposit, play, withdraw. Anti-fraud controls make the circle less decorative and more consequential. A casino may need to confirm that the source and destination belong to the same person, or assess an alternative before sending funds. Where the route changes, the transaction may require more scrutiny.
For players, this can make consistency useful. Keeping the payment source tied to the same customer identity reduces avoidable uncertainty when funds are returned. It does not override closed-loop rules or guarantee that a particular method will be accepted for withdrawals. The operator’s terms determine the route, while the underlying control is clear: payouts are generally directed back to the source used to fund play, and alternatives may bring further verification.
The money has a route home.
Why a Deposit Can Be Instant and a Withdrawal Slow
A payment can arrive at a casino account quickly without making the journey back equally quick. A specialist review describes card deposits as potentially instant, while a payout may take several business days. The difference is not a contradiction: the two transactions pass through different stages, and a visible account balance does not mean a withdrawal has already been approved or sent.
Casinos That Accept Maestro in the UK
A deposit is initiated by the customer and can be confirmed electronically. A withdrawal begins with a request that the casino must process. Before funds leave, the operator’s internal approval procedure may need to be completed. That introduces a stage absent from the simple act of paying in. The payment method matters, but it is not the entire clock.
Verification can add further time. A specialist review notes that a first withdrawal may take longer while the account is being checked. If identity or account details remain unconfirmed, the payout cannot be treated as though it were already moving through the payment network. The account’s verification status therefore affects the timetable alongside the casino’s own approval process.
This distinction matters when considering an Entropay casino withdrawal in the UK. A quick deposit, where a payment route is accepted, would not by itself establish that a payout using that route would be equally quick. Nor does the word “card” settle the question: deposit speed and withdrawal speed describe separate processes, not a matched pair of promises.
There is a small drama in the difference. Money entering a casino account can look immediate; money leaving it has to pass through a gate staffed by procedure. That gate may involve approval and checks before any payment provider begins its part. The customer-facing balance records the first event, not completion of the second.
A specialist review identifies internal processing and the state of verification as factors in withdrawal speed. These are operator-side considerations, so a payment route cannot erase them. A fully checked account and a completed approval process leave fewer unresolved steps; an outstanding check can hold up a payout even when the deposit was credited without delay.
Withdrawal Timetables
- Deposit speed does not guarantee withdrawal speed
- Internal operator approval is a separate stage from the payment transfer
- Account verification status directly affects payout timing
- Processing delays occur at the operator level before the payment network is engaged
The same caution applies to searches for an Entropay casino list: a list of payment names, where one exists, cannot tell how long a particular withdrawal will take. The meaningful timetable is the one attached to the operator’s payout process and the account’s verification status. An instant deposit is a statement about money arriving. It is not a departure time.
How to Confirm a Payment Method Before Depositing
A payment logo on a casino’s public page is a starting point, not proof that the method can be used on a particular account. Availability can depend on the customer’s location, account status and the payment product itself. The decisive check is the cashier after signing in, before any transaction is submitted.
For Entropay, no particular UK casino can be confirmed as accepting it. A name in an old list or a general mention of e-wallets would not establish that the method appears for a current British account. The cashier should show Entropay as an available option for that account; if it is absent, a deposit should not be attempted through a substitute route that happens to share some details.
The same care applies to cards. A specialist review may list Visa or Mastercard, but that does not establish current UK availability or confirm that every card product is eligible. The cashier’s displayed options need to match the actual card, and credit-card payments for gambling are not permitted at UK-licensed casinos.
Currency deserves its own check before the first payment. A specialist review may state that GBP is supported, but the account’s selected currency should still be confirmed in the cashier. If the account is set to another currency, conversion may enter the transaction even when the payment method itself is available.
Casinos That Accept Tether in the UK: What’s Verified
The useful record is therefore specific: the method shown, the account it is shown for, the currency selected and the payment details accepted by the cashier. Availability is not a permanent property of a brand name; it is a condition of a particular account at a particular point in time. That is less tidy than a logo. It is also more useful.
What Makes a Casino Payment Route Suitable
A payment route is suitable when its account details fit the identity held by the casino, and the same route can be used consistently for the transaction. The useful test is not whether a brand sounds familiar. It is whether the account and payment source belong to the same person and can be presented as part of one coherent record.
That matters because a mismatch can turn a routine transaction into an avoidable question. A casino account in one name paired with a payment account in another may prompt checks about ownership. Matching details do not guarantee that a transaction will be accepted, but they remove one basic source of friction.
The cleanest arrangement is often one named account used for both deposit and withdrawal. It keeps the payment history legible: funds enter through an account belonging to the customer, and the same account remains part of the record when money is returned. Switching between accounts or mixing personal and shared payment details can make that trail harder to explain.
A route associated with Entropay should be judged by those practical standards rather than by the name alone. A familiar label cannot settle whether the account details align or whether the route suits a particular transaction. The account holder remains central.
Using a single named account for both deposits and withdrawals creates a coherent record and reduces avoidable friction during ownership checks.
There is a small social history in this preference for matching names. Digital payments promise to make money less visible, but regulated gambling brings the identity back into view. The transaction is not simply a movement between boxes on a screen; it is attached to a person, an account and a record that must make sense together.
Consistency is plain, not glamorous. But payment systems tend to reward the plain.
When Fast Payouts Depend on More Than the Method
A payment route can be quick at the point money leaves a casino and still sit behind an operator’s approval queue. The transfer is only one part of a withdrawal: the casino must first review the request, and an account that has not completed verification may need further checks before funds are released. The clock therefore does not belong to the payment method alone.
A specialist review identifies PayPal, open banking services and debit cards connected to fast payout systems among the quicker withdrawal routes. That comparison describes the transfer leg, not a promise about the time from submitting a request to receiving money. A casino’s own processing arrangements and the status of the account remain part of the journey.
Casinos that accept Monzo in the UK: what to check
This distinction matters when assessing claims about a particular casino payment option. A method’s appearance in a cashier, or a reputation for rapid transfers, cannot establish how quickly that operator will approve a payout. Nor does a fast deposit demonstrate that the withdrawal process will move at the same pace. The two directions of a transaction have different stages.
Verification is not merely a formality added after a delay has begun. If it is incomplete when a withdrawal is requested, the operator may need to resolve that first; where the account is already fully verified, that source of additional processing is less likely to intervene. The casino’s internal review still applies.
The sensible measure is thus not a method’s speed in isolation, but the combination of operator approval, completed account checks and the route’s transfer performance. A specialist review also notes that withdrawal speed depends on the casino’s approval process and whether verification is complete. The method is only one moving part.
Casinos That Accept Apple Pay in the UK
No shortcut in the name.
UK Rules That Shape Casino Payments
A payment brand does not sit outside the rules governing the money behind it. In the UK, credit-card payments for gambling have been prohibited since 14 April 2020, and the restriction remains in force. Remote gambling licensees cannot accept a credit card as a casino payment, including when credit-card funds are channelled through a money service business. Nor can they accept wallet payments where that wallet permits credit-card money to be used for gambling.
That distinction matters when considering a named payment service such as Entropay: the name alone does not establish which funding source is involved or whether a transaction is permitted. A payment route must be considered in light of how it is funded, not simply how it appears in a cashier. The credit-card rule is a market-wide boundary, not a judgement on a particular brand.
A separate safeguard applies before a new customer makes a first deposit. UKGC requirements oblige remote operators to prompt the customer to set a financial limit at that point. Account-level controls must also remain accessible, so the limit is not merely a prompt encountered once and then forgotten. The measure places a pause before the first transfer of money, and makes financial limits part of account management rather than an obscure payment setting.
The two rules address different risks. The credit-card restriction defines which funds operators may accept for gambling; the limit prompt gives customers a point at which to set a boundary on spending. Neither rule confirms that a particular payment method is available at a particular casino. That question still depends on the operator’s current cashier and the transaction’s eligibility.
A regulated payment system is not a guarantee of frictionless play. It is a framework of boundaries, some visible before a deposit and some built into the route money can take. Dry, but consequential.
Why can a fast-payout casino still delay my withdrawal?
A fast payment method does not skip the casino’s approval process. Withdrawals can take longer if the account is not fully verified, especially for a first payout.
Why must withdrawals return to the deposit method?
Returning funds to the original source is a common UK anti-fraud and money-laundering control. An alternative route may require additional verification.
Which payment methods are accepted in Great Britain?
UK casinos commonly accept Visa and Mastercard debit cards; some also offer PayPal, bank transfers or open banking, Paysafecard, Skrill, Neteller and Apple Pay. Check the casino cashier, since available methods vary by site and account.
Can I deposit in GBP?
Yes, GBP is supported at the sites covered. Check your account currency before depositing to avoid a possible conversion.
What is the current minimum deposit?
The minimum deposit usually starts at £10–£20, depending on the payment method.
Material created by the team Pure Casino UK Guide